This guide explains receivables fundamentals and how to manage them with evidence-based controls aligned with Investopedia-style definitions. It provides objective background on what “receivables” means in accounting, why aging matters, and how businesses assess credit exposure, collect payments, and protect cash flow without assumptions.
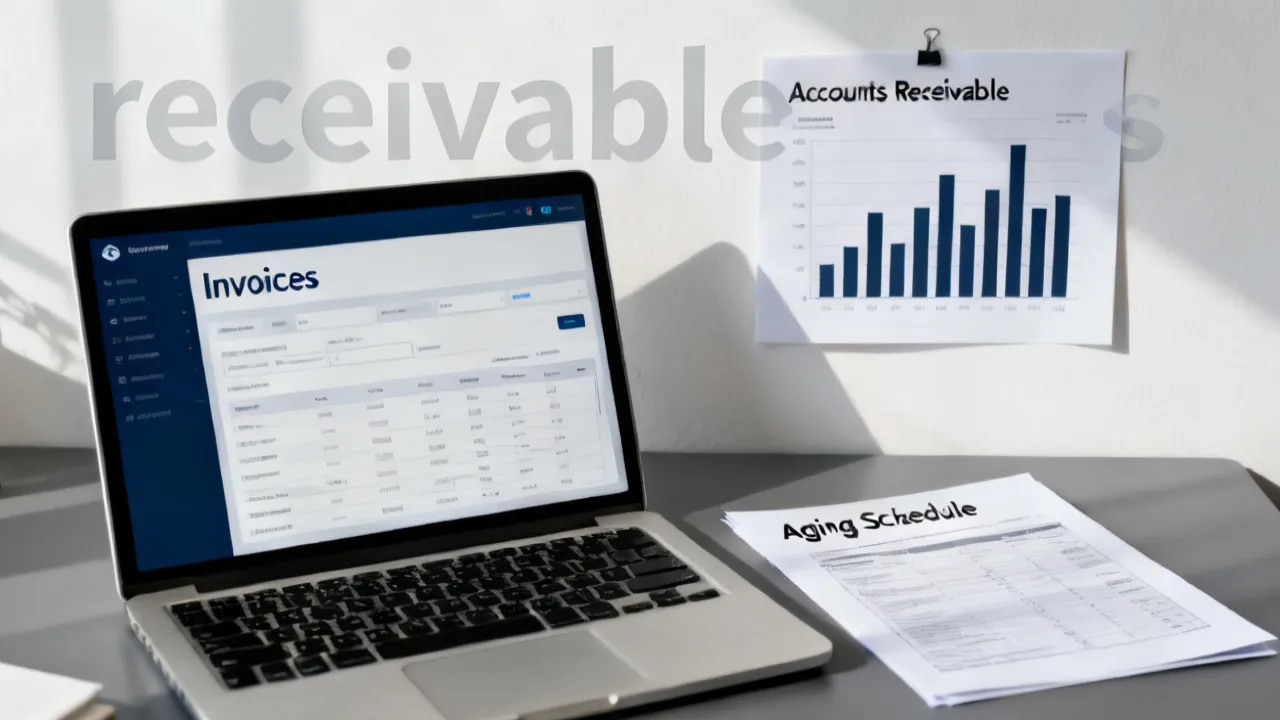
Receivables are amounts customers owe your business for goods or services delivered, and they often represent a major portion of working capital. When organizations manage receivables with a disciplined process—clear credit policies, an aging review, and a consistent collections rhythm—they improve cash predictability while controlling credit losses. This article uses the concept of Receivables Investopedia-style accounting clarity to build a professional, risk-aware approach that you can apply regardless of industry.
In plain terms, receivables sit between “revenue recognized” and “cash received.” The gap is where timing risk, credit risk, and operational risk can emerge. A well-designed system reduces uncertainty by answering practical questions: Who owes, how long they have owed, how likely they are to pay, and what action is appropriate.
Although the phrase Receivables Investopedia is often used as a shorthand for authoritative definitions and neutral explanations, the operational challenge is the same everywhere: receivables are only valuable if they ultimately convert into cash (or are otherwise settled) in a reliable timeframe.
Many companies treat receivables management as a back-office activity—something to “handle” after invoices are issued. In practice, the highest-performing organizations treat receivables as a system that begins at order entry and ends at cash application. That system includes credit decisions, accurate invoicing, dispute prevention, and a collections workflow that respects both customer relationships and risk thresholds.
This matters because receivables can quietly become a drag on performance even when sales growth looks healthy. A company can appear successful in profit terms while simultaneously becoming liquidity-constrained due to slower collections. By contrast, companies that manage receivables proactively often experience smoother cash cycles, fewer surprises, and improved resilience during economic stress.
From an accounting perspective, receivables generally appear as current assets when expected to be collected within a normal operating cycle. They are commonly associated with trade accounts receivable, notes receivable, and other short-term obligations owed to the company. The core idea is consistent: receivables quantify your claim against customers, not cash in hand.
Because customers can delay payment—or default—financial statements typically incorporate mechanisms for credit risk. A common one is the allowance for doubtful accounts (often paired with an aging-based or probability-informed estimate). The purpose is not to “guess” in an arbitrary way; it is to match expected losses to revenue periods using defensible methods.
In practice, companies must reconcile three perspectives:
When those perspectives align, receivables become a credible and auditable asset. When they do not, receivables can become “financial fiction”—balances that exist in reports but fail to convert into cash at the pace management expects.
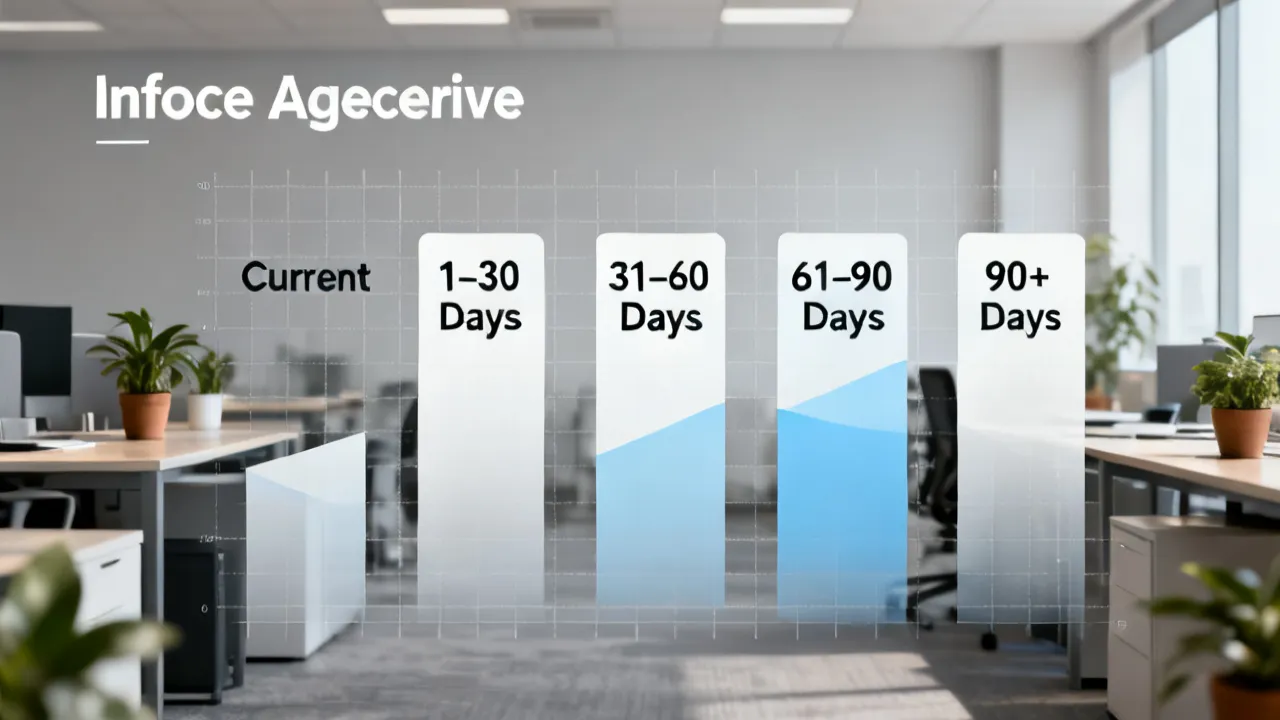
An aging schedule groups receivables by how long an invoice has been outstanding, such as “current,” “1–30 days,” “31–60 days,” “61–90 days,” and “over 90 days.” This segmentation matters because the probability of collection generally declines as invoices age. The aging view helps management prioritize actions and prevents staff from treating all receivables as equally collectible.
Aging also makes performance visible. Without aging, a company might only see total receivables. With aging, management can see whether collections are improving in the early buckets but deteriorating in later buckets, or whether the whole distribution is shifting unfavorably.
For objective governance, many organizations combine aging with transaction history (e.g., disputes, deductions, prior payment patterns) and current credit standing. The operational goal is to convert receivables management from an end-of-month “cleanup” into a continuous risk process.
It’s useful to understand that aging is not only a collections tool; it is a diagnostic tool. When aging changes suddenly, it often signals upstream problems such as billing defects, changes in fulfillment practices, contract disputes, or credit policy changes.
For example, if invoices move from “current” into “1–30 days” faster than usual after a pricing update, that may indicate invoice issuance delays or misapplied payment terms. If invoices jump directly to “over 90 days,” that may indicate severe disputes, customer insolvency, or a breakdown in escalation.
A key tension in receivables management is growth vs. risk. A company can increase sales, but if it relaxes credit terms or approves customers without adequate assessment, receivables can grow faster than collection capacity. That growth can temporarily boost reported revenue while increasing the likelihood of write-offs or cash strain.
Credit exposure is influenced by several factors:
In a structured receivables program, these factors are reflected in policies, workflow ownership, and measurable outcomes (e.g., days sales outstanding, dispute cycle time, and bad debt rate).
However, credit exposure is not always obvious from credit limits alone. Exposure can concentrate in ways that a credit analyst might not immediately see: for example, through off-book agreements, unbilled work-in-progress disputes, or credit notes that are slow to issue. Some companies also unintentionally extend credit through operational delays—promises made to customers that do not match contract terms.
To manage this effectively, organizations should treat credit exposure as a dynamic variable. It changes with billing accuracy, contract compliance, fulfillment timing, and customer communication quality. A mature system therefore combines credit policy with operational monitoring.
The request mentions supplier details, and it’s important to clarify roles objectively. Suppliers are often discussed on the payables side (what your company owes), while receivables focus on what customers owe. However, supplier-related considerations can still influence receivables indirectly:
Put differently: suppliers do not “create receivables,” but supplier performance can affect how smoothly receivables convert into cash.
To make this practical, consider a service business that depends on subcontractors. If subcontractor work is late or lacks proper documentation, the service firm might be unable to invoice correctly. That can lead to “underbilling” (which means fewer receivables) but also to later invoice revisions or disputes (which means those receivables may become harder to collect).
Even though suppliers are not the direct counterpart in receivables, operational dependencies matter. A comprehensive cash cycle view includes both receivables and payables, because the business’s liquidity depends on the combined timing of customer payments and supplier payments.
Receivables are not just a balance sheet line; they influence liquidity. When collections slow, cash may become insufficient to fund payroll, inventory replenishment, or required obligations. Many finance teams monitor working capital indicators to detect early stress—particularly when receivables growth outpaces revenue growth or when aging trends upward.
For objective benchmarking, it’s safer to track internal trends and corroborate them with publicly available industry research from reputable sources such as:
This article avoids speculative or unverifiable numeric claims. Instead, it focuses on controls and decision logic that remain valid across business models.
A helpful way to conceptualize receivables in liquidity terms is to look at the “cash conversion cycle” and related measures. Even without heavy mathematical complexity, you can ask: How much cash is tied up in receivables today compared with last quarter, and what is changing—collections speed, invoice volume, or dispute behavior?
When receivables rise faster than operating cash flow, the gap can come from:
Tracking these drivers allows finance leaders to distinguish between “good growth” that is still cash-efficient and “growth with hidden cost.”
Industry practitioners often converge on several themes when designing receivables governance. Below is an expert-oriented, practical set of controls you can adapt.
Receivables quality starts at billing. Controls commonly include invoice templates, mandatory fields, and automated checks (e.g., order number, service period, pricing references). The goal is to reduce errors that later become customer disputes—disputes that delay payment even when the underlying obligation is valid.
Standardization is not only about formatting. It is about completeness and traceability. A disciplined invoice should allow the customer to validate quickly. If the customer cannot easily match an invoice to a purchase order or contract, the invoice is more likely to get stuck in internal approval workflows or get contested.
Invoice validation controls often include:
From a risk perspective, the highest ROI action is often to eliminate repeat billing defects. If the same issue causes disputes month after month, it likely indicates a process weakness that will drain cash through delayed payments.
Credit terms should reflect customer risk. Many organizations implement credit approval workflows with tiered limits. If a customer exceeds an internal risk threshold, the company may require a shorter payment term, a deposit, or additional documentation.
Credit approval thresholds are most effective when they are structured as a decision tree rather than a vague policy statement. For instance:
Additionally, credit policy should clarify what happens when limits are breached. Some organizations allow orders to proceed but then manage the increased risk later in collections; others halt further sales when limits are exceeded. The best choice depends on business strategy, concentration risk, and customer relationship priorities, but the key is that the decision must be intentional and consistent.
Credit approvals should also be periodically revisited. A customer’s risk profile changes due to macroeconomic conditions, operational issues, or changes in ownership. A periodic review process ensures that credit decisions do not become outdated.
Finally, credit policy must coordinate with sales. Sales teams need to understand the “why” behind credit decisions. When credit is perceived as arbitrary, customers may get frustrated, but when credit decisions are framed as predictable rules and time-bound reviews, cooperation tends to improve.
Accounting standards support recognition of expected credit losses using reasonable and supportable data. While specific models differ by jurisdiction and accounting framework, experts emphasize consistent methodology and audit-ready documentation. Aging schedules, historical loss rates by cohort, and forward-looking considerations (when permitted and supportable) are typical inputs.
From a practical perspective, the allowance process should not be treated solely as a year-end accounting exercise. It is more useful when it feeds operational decisions:
When the allowance model consistently overestimates or underestimates losses, it can create distortions. Overestimation can suppress profitability and cash planning. Underestimation can delay recognition of credit issues and increase surprises in financial statements.
Therefore, allowance methodology should include governance over model updates. If you revise assumptions, you should document why, how, and what evidence supports the change. This protects credibility with auditors and internal risk committees.
Also consider how “dispute” interacts with allowance estimates. Disputes do not always equal credit losses, but persistent disputes can be a leading indicator of credit trouble or operational breakdown. A thoughtful process distinguishes between:
This distinction helps ensure the allowance does not conflate operational friction with true credit risk.
Collections should be proactive, not reactive. A common expert pattern is to define actions by invoice age—such as reminder emails, calls, account reconciliation, escalation to senior collections, and eventual legal referral when appropriate.
Crucially, escalation rules must be coordinated with dispute handling so legitimate issues are resolved quickly rather than endlessly re-queued.
A well-designed collections workflow typically includes:
Escalation policies should also consider customer relationships. For some industries (e.g., enterprise procurement environments), too aggressive collections language can harm long-term contracts. The best teams use escalation as a structured escalation ladder—firm, respectful, and consistent.
Additionally, collections workflow should support resolution. Many receivables fail to convert to cash not because customers refuse to pay, but because they cannot reconcile the invoice quickly. In those cases, a collections agent who can quickly coordinate with billing or customer service can reduce friction and accelerate payment.
Effective teams track more than a single metric. Relevant KPIs often include:
For definitions and neutral context, readers frequently cross-reference Receivables Investopedia explanations alongside professional accounting resources. The important point is to apply metrics consistently, not to chase one “top” number.
To make KPIs operationally useful, they should be broken down by dimension:
This breakdown helps identify where improvements are most needed.
For example, a stable overall DSO might conceal a deterioration in one segment that is offset by better performance elsewhere. Without segmentation, management may miss emerging risk.
To ground the discussion, consider a few objective scenarios.
Scenario A: Invoices age upward after a customer merger. The company may be right to expect consolidation issues or new approval layers. The company should not automatically label this as credit deterioration. An aging review combined with customer contact history helps differentiate temporary friction from a structural credit deterioration. A good practice is to create a “temporary hold” classification only if there is documented evidence, and to re-evaluate quickly after the merger integration phase.
Scenario B: High dispute volume increases days to cash. Instead of focusing only on chasing overdue invoices, an expert team links disputes to root causes: billing errors, missing delivery documentation, or unclear contractual terms. Fixing upstream causes typically lowers both disputes and bad debt. In addition to process fixes, improving dispute reason codes and resolution SLAs provides clear accountability and helps quantify improvements over time.
Scenario C: Sudden increase in write-offs in one segment. That pattern can indicate a credit policy gap, a concentration risk, or a contract problem. Experts respond by tightening approvals for that segment and reviewing contract terms, while reassessing the allowance method with evidence. The response should include examining whether the write-offs correspond to the aging cohorts predicted earlier. If write-offs are much higher than expected, it may indicate that the allowance model is not capturing a new risk environment.
Scenario D: Concentration risk—one large customer slows payment. In many businesses, a few accounts represent a large portion of receivables. If one large customer delays payment, overall DSO might worsen quickly. A mature receivables program uses concentration limits, enhanced monitoring for top accounts, and early communication workflows. It may also involve setting aside additional credit protections such as tighter payment terms, progress billing, or collateral where appropriate and legally permitted.
Scenario E: Recurring invoicing fails due to service documentation issues. In subscription or services models, invoices may be generated automatically. However, if service confirmation evidence is missing—such as timesheets, usage logs, or acceptance certificates—customers may contest invoices. The solution is not necessarily a collections push; it can be an integration improvement between service delivery systems and invoicing. When operational evidence is automated and consistent, dispute rates typically drop.
These scenarios illustrate that receivables problems are rarely purely “collections problems.” They are usually process problems, credit problems, or evidence problems that surface as payment delays.
| Approach | How it works | Top used for | Conditions / requirements |
|---|---|---|---|
| Aging-based prioritization | Sort receivables by days outstanding and act by age bucket | Operational collections workflow | Accurate invoice dates; consistent aging logic; dispute tagging to avoid misclassification |
| Credit tiering and limits | Assign credit limits and terms based on customer risk tier | Preventing excessive exposure | Documented approval rules; periodic credit reviews; monitoring of limit breaches |
| Allowance for doubtful accounts | Estimate expected credit losses using supportable data and defensible methodology | Financial statement integrity | Audit-ready assumptions; consistent historical data; governance over model updates |
| Invoice quality and validation controls | Reduce billing errors through standardized templates and checks | Reducing disputes and payment delays | ERP/invoicing governance; clear ownership of billing corrections |
| Customer dispute workflow | Track disputes, evidence, and resolution timelines | Minimizing “stuck” receivables | Dispute reason codes; reconciliation steps; SLA for resolution |
In practice, the strongest programs do not rely on one approach. They use a “stack” of controls that reinforce each other. Aging helps prioritize. Credit tiering prevents excessive risk. Allowance methods improve financial transparency. Invoice quality reduces disputes. Dispute workflows reduce stuck invoices.
When implementing these approaches, it is often better to ensure data accuracy and workflow discipline first, before trying to adopt complex analytics. Many organizations can improve cash outcomes substantially just by tightening billing and dispute handling, even before sophisticated credit models are introduced.
For background definitions and accounting context, the following types of authoritative sources are commonly used:
When teams cite Receivables Investopedia terminology, it is typically as a definition anchor. For decision-making and measurement, experts supplement definitions with their applicable accounting guidance and internal audit requirements.
Because accounting rules vary by jurisdiction and reporting framework, companies should ensure their receivables impairment and allowance methodology aligns with their local requirements and their external auditor’s expectations. If you operate across multiple regions, you may need a harmonization approach that preserves compliance while maintaining operational consistency.
Below is a practical improvement sequence that many finance leaders adopt. The emphasis is on measurable controls and governance.
Calculate DSO, review aging distribution, and quantify disputed and past-due volumes. Use consistent time periods so trends are comparable. If you already have aging reports, verify that dates, customer classifications, and dispute tags are accurate.
A baseline is not only numerical. It should include process baseline information such as:
These additional baseline elements are often the difference between superficial improvements and durable change.
Segment receivables by customer, invoice type, and dispute category. Then ask: Is the issue timing, billing accuracy, credit policy, or dispute resolution speed? Expert teams avoid treating the problem as one-size-fits-all.
Root cause analysis works best when you adopt a structured approach:
If you find that a small number of customers represent most of the late-stage aging, you can focus remediation on credit decisions and customer-specific workflows rather than applying broad, inefficient tactics.
Implement required fields, validation rules, and a clear process for corrections. Reduce preventable rework before invoices are issued. Many organizations discover that small billing defects drive disproportionate collection friction.
Invoice readiness controls can be expanded beyond basic validation. For example:
These controls require effort, but they typically deliver cash outcomes quickly because fewer invoices are disputed and fewer payment cycles are delayed by clarification.
Ensure credit approvals reflect customer risk. Refresh credit checks periodically and define what triggers re-review (e.g., limit breaches, sustained past-due aging, or changes in payment patterns).
Credit monitoring can be designed as a tiered system:
When credit is monitored based on behavior, you often detect issues earlier than when relying solely on periodic financial statements. Payment behavior can reflect distress before formal insolvency indicators become obvious.
Also consider how you treat disputed amounts within credit monitoring. If a customer is disputing frequently, even if not always due to non-payment, the overall risk profile may increase because it indicates either operational friction or potential unwillingness to pay.
Create a timeline of actions by aging bucket. Ensure collectors coordinate with billing and disputes teams. Define escalation paths and document the rationale for legal or recovery actions.
Escalation workflows typically require clear roles and SLAs. For example:
If those roles are unclear, escalation becomes chaotic and the customer perceives inconsistency. The result can be slower resolutions and increased friction.
Additionally, collections should be supported by robust data. A collector should be able to see:
In modern implementations, these data are integrated into a single customer receivables view. Even if you do not have a sophisticated system, you can create “receivables snapshots” to reduce information gaps.
Review whether the allowance approach aligns with the actual loss experience and aging behavior. Confirm assumptions are supportable and documented for audit purposes.
Reassessment should include a “back-testing” mindset: do the allowances predicted for certain aging cohorts match actual outcomes? If not, the methodology may require refinement. Common causes of mismatch include:
When adjustments are made, document both the evidence and the reasoning. The allowance process is not merely accounting compliance; it is a risk representation that should reflect reality as closely as possible.
Establish recurring reviews (weekly operational; monthly financial). Improvements should be evaluated through reduced dispute cycle time, improved aging distribution, and stabilized cash conversion.
Continuous improvement also means learning from customer behavior. If certain customers consistently dispute invoices for valid technical reasons, you may need customer-specific documentation procedures. If certain reason codes recur, you may need systematic improvements to billing or contract interpretation.
A useful practice is to run structured monthly “receivables performance reviews” that cover:
These reviews should culminate in action items with owners and deadlines. Without ownership, improvement becomes a discussion rather than a program.
To make these requirements practical, consider the “minimum viable governance” that many organizations implement first:
As maturity increases, companies often expand with automated credit checks, integrated dispute portals, and more advanced analytics. But governance fundamentals are what keep the system consistent and reliable.
Receivables are amounts due from customers or other parties for goods or services delivered, recorded as assets to the extent collection is expected. They represent a contractual claim, not cash already received.
Effective management accelerates collections and reduces delays caused by disputes or credit issues. When receivables convert into cash more reliably, the company can fund operations with less liquidity strain.
An aging schedule groups invoices by how long they are outstanding. Because collection likelihood typically decreases as invoices age, aging helps prioritize follow-up and supports more accurate credit risk monitoring.
Directly, receivables relate to customers who owe money. However, supplier performance can indirectly affect receivables through delivery reliability, documentation, and the quality of invoicing evidence used to support claims.
Companies typically use evidence-based methods such as historical loss patterns by aging cohort and, where permitted, forward-looking information that is supportable and consistently applied. The approach must be documented to satisfy audit and governance requirements.
Common KPIs include DSO, past-due ratio, dispute rate, dispute cycle time, collections effectiveness by aging bucket, and the allowance coverage ratio (where applicable). Use internal trend analysis and consistent definitions.
Experts typically respond by tightening invoice validation, improving documentation, and implementing an SLA-based dispute workflow with clear reason codes and escalation paths. Reducing billing friction often improves days-to-cash more than chasing overdue invoices alone.
Use credit tiering and approval thresholds, monitor exposure, and adjust terms when risk changes. The goal is to maintain sales while ensuring that collectability remains within an acceptable risk framework.
Receivables are central to business liquidity, and the definition-level clarity associated with Receivables Investopedia is only the starting point. The value comes from disciplined controls: standardized billing, credible credit decisions, aging-based prioritization, evidence-based allowance processes, and a collections workflow that resolves disputes quickly. When those elements work together, receivables become a predictable engine for cash conversion rather than a lingering uncertainty on the balance sheet.
To make that outcome durable, the key is to build a system with feedback loops. Billing controls reduce disputes; dispute resolution speed improves cash conversion; collections discipline prevents risk from compounding; credit monitoring updates exposure; allowance methodology reflects evidence; KPI dashboards reveal early warning signals. In that integrated system, receivables management stops being a reactive function and becomes a continuous risk management capability.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
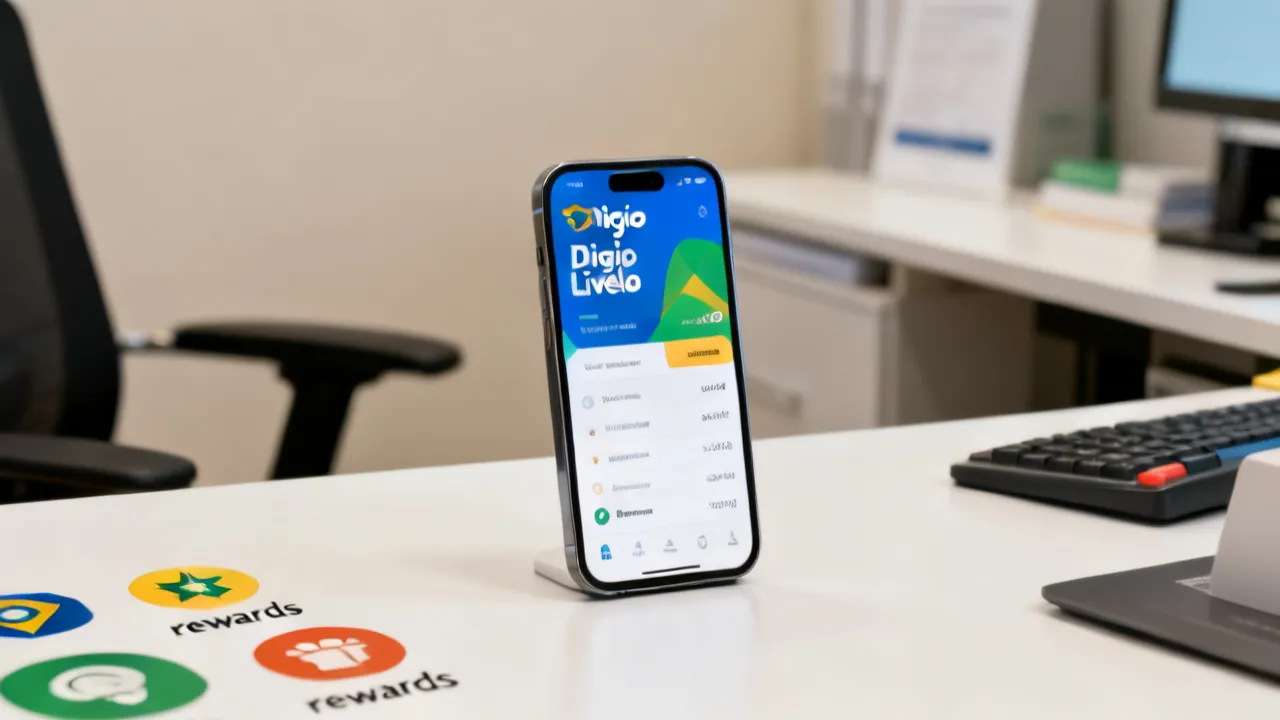
Digio Livelo Explained: Rewards Integration and Use
This guide explains how Digio Livelo works for earning and using rewards, what to verify before you start, and how to choose sensible redemption options. “Digio Livelo” refers to a rewards relationship between Digio’s digital banking/payment experience and Livelo’s loyalty ecosystem. Practically, it’s about matching your spending or engagement to reward accrual, then selecting redemptions that fit your goals.
Receivables Explained with Investopedia Insights and Risk Controls
This guide explains receivables fundamentals and how to manage them with evidence-based controls aligned with Investopedia-style definitions. It provides objective background on what “receivables” means in accounting, why aging matters, and how businesses assess credit exposure, collect payments, and protect cash flow without assumptions.
Accounts Receivable Guide: Investopedia Insights for Clarity
This guide explains how accounts receivable work, how they’re valued and managed, and how firms interpret them in decision-making. Background context covers the Receivables concept referenced by Investopedia, common risks like credit exposure and timing gaps, and the role of policies, documentation, and estimates such as allowances. The focus is practical and objective for analysts and operations leaders.
Receivables: How to Interpret and Manage Credit Risk
Receivables are the lifeblood of many businesses because they represent money owed by customers. This guide explains how receivables are analyzed, why payment terms matter, and how “Receivables Investopedia” concepts help standardize thinking about liquidity and credit risk. Objective background follows, centered on accounting definitions, risk signals, and common management practices.
Bambora Payfac: A Practical Guide for Merchants
Bambora Payfac helps merchants structure card and digital payments through a streamlined payment facilitation model. This objective guide explains what payment facilitation is, how onboarding and compliance typically work, and what merchants should evaluate—pricing transparency, risk controls, settlement timing, and operational responsibilities—so you can choose an approach that fits your business needs.
Understanding Accounts Receivable and Investopedia Insights
This guide explains how accounts receivable work, how to interpret “Receivables” definitions (including perspectives aligned with Investopedia), and how to manage invoice collections with disciplined policies. Accounts receivable refers to money customers owe from credit sales. It sits on the balance sheet as a current asset, and its quality affects cash flow, risk, and working-capital decisions.